FinnOne Neo®

 Lending

 Transaction Banking
 Financial Inclusion
 Technology



FinnOne Neo® 9.0 brings AI-powered lending intelligence to every stage of the loan lifecycle, built to help banks and finance companies across Vietnam, the Philippines, Sri Lanka, Indonesia, and Malaysia move faster, decide smarter, and recover more.
Lending in Southeast Asia has gotten harder to get right. Borrowers expect a decision almost instantly. Regulators expect that decision to be airtight. And boards expect growth that doesn’t quietly load up the balance sheet with risk. We’ve spent the past year talking to lenders across Vietnam, the Philippines, Sri Lanka, Indonesia, and Malaysia about exactly this tension, and it shows up everywhere in how we built FinnOne Neo® 9.0.
The platform was unveiled at the inaugural Nucleus Synapse Vietnam in Hanoi, and it’s built around one idea: eliminate the bottlenecks that slow down origination, loan management, and collections, so AI stops being a slide in a strategy deck and starts showing up in how decisions get made.
Why FinnOne Neo® 9.0 Matters for Southeast Asia’s Financial Institutions?
The goal is straightforward, help financial institutions make every lending decision faster and more consistent, without piling on operational weight. What that means in practice, though, looks different depending on where you sit.
In Vietnam, customers are already digital-native and pay by QR by default, so the platform must keep pace with behaviour that’s already ahead of most legacy systems. In Philippines, millions of people are entering formal credit for the first time, and the challenge is onboarding them quickly without letting KYC standards slip. Sri Lanka’s lenders live and die by portfolio discipline, the priority there is catching risk before it turns into a loss, not after. Indonesia has one of the region’s largest underbanked populations and a fast-growing Islamic finance sector, so scaling responsibly across both conventional and Shariah-compliant lending matters more than scaling fast. And Malaysia’s regulatory environment is among the most sophisticated in the region, which means decisioning must hold up to scrutiny across an increasingly complex mix of products.
FinnOne Neo® 9.0 was built with all five of these realities in mind, not as an afterthought but as the design brief.
Key Capabilities of FinnOne Neo® 9.0
Here’s what changed across customer acquisition, loan servicing, collections, and mobility.
1. Customer Acquisition System (CAS): Faster Onboarding, Broader Reach
FinnOne Neo® 9.0 expands support for Finance Against Security (FAS), Co-Lending, Omni Loan, and Gold Loan processes, letting banks serve a wider range of products without adding operational drag. That’s a big deal in the Philippines, where product variety is often what determines whether a lender can reach underserved segments at all and in Indonesia, where Gold Loan and Islamic financing remain two of the most effective ways to bring customers outside conventional banking into the fold.
Onboarding itself also got sharper. AI-Powered Document Validation checks document quality and type automatically at the point of upload, cutting down on rework and tightening KYC, exactly the kind of thing that matters when most applications are coming in through a phone, not a branch. On the business-lending side, Verified Corporate Data Fetch pulls authenticated business information through URN-based verification, which cuts manual data entry and reduces fraud risk for SME and corporate applicants, useful anywhere, but especially so in Malaysia’s more sophisticated corporate and Islamic banking segment.
SME and Corporate lending picked up facility-level enhancements too, streamlining credit processing for the kind of complex business lending that’s becoming more common as corporate lending matures across Indonesia and Malaysia alike.
Explore more – FinnOne Neo® Loan Origination System (LOS)
2. Loan Management System (LMS): Servicing Built for Scale and Trust
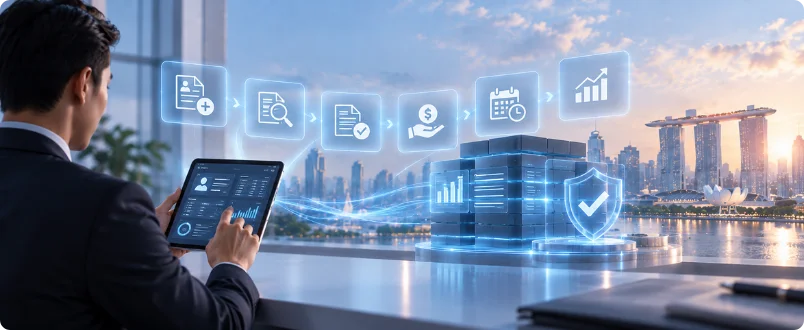
On the servicing side, Continuous OFAC Compliance Monitoring automates sanctions screening on an ongoing basis, most relevant for banks with US-dollar correspondent relationships or cross-border trade finance exposure, a growing consideration as institutions like Malaysia’s larger banks deepen international banking ties.
Repayment flexibility got real attention too. AutoPay Registration and Closure make it easier to set up and close recurring payments through card and ACH channels, which cuts down on missed payments without adding friction for the customer. Differential Interest Optimization calculates interest against actual outstanding balances rather than static schedules, which is a small change with a real effect on transparency. And for institutions dealing with distressed portfolios, Bankruptcy Restructuring Automation handles principal adjustment and repayment schedule regeneration without someone manually rebuilding a loan from scratch.
One more worth flagging: Credit Bureau Integration pulls bureau data into a single borrower profile, which sounds administrative until you’re the underwriter trying to piece together a credit picture from three different sources.
Explore more: FinnOne Neo® Loan Management System (LMS)
3. Collections: Predictive Intelligence Where It Matters Most
Collections is where the AI-first approach pays off most directly, and probably where lenders will feel the difference fastest.
PTP Default Prediction flags promise-to-pay commitments that are likely to break, before the due date, not after, so teams can prioritise and follow up while there’s still time to change the outcome. For finance companies in Sri Lanka running disciplined recovery operations, that’s the difference between reacting to a default and getting ahead of one.
The Unified Digital Payment Experience brings QR codes, cards, bank transfers, and other locally supported methods into one configurable interface, meeting Vietnamese and Indonesian customers exactly where they already pay. Intelligent Repossession Assessment adds structure to asset inspection and valuation before repossession happens, and Region-Based Repossession Workflows let that process follow local practice rather than a one-size-fits-all template – genuinely useful in archipelagic markets like Indonesia and the Philippines, where “region” can mean a very different set of rules depending on where you are.
On the operational side, Time Zone Visibility & Contact Control keeps outreach within permitted hours by local regulation, and Always-On System Availability means collections doesn’t grind to a halt during end-of-day or batch processing windows.
Explore more: FinnOne Neo® Collections
4. Mobility: Digital-First, By Design
Mobile isn’t a secondary channel in most of Southeast Asia , it’s often the only one. FinnOne Neo® 9.0 treats it that way. Background Privacy Protection and Screenshot Prevention Controls keep sensitive customer and financial data from leaking through app previews or screen captures, and Federated Mobile Authentication (MSAL) gives customers the same secure login experience whether they’re on mobile or web.
5. Regulatory Compliance and Data Integrity: Built for Trust
Compliance runs through every module rather than sitting off to the side. DPDP-Compliant Consent Management handles customer consent through an auditable interface mechanism – the kind of rigour that data protection frameworks in Indonesia and Malaysia are increasingly expecting as standard, not a nice-to-have. And Inclusive Lending Support for Persons with Disabilities helps institutions meet regulatory requirements while genuinely widening who gets access to credit, a priority more regulators across the region are starting to write into policy.
Built to Move as Fast as the Region Does
What ties all of this together is agility, the platform’s, not just the roadmap’s. Southeast Asia isn’t one regulatory regime or one technology stack; it’s five markets moving at five different speeds, each layering new compliance mandates, payment rails, and core banking integrations on top of what came before. A platform that can’t flex with that reality becomes a liability the moment the ground shifts, whether that’s a new DPDP-style data mandate in Indonesia, a fresh BSP directive in the Philippines, or another payment method Vietnam’s customers adopt before anyone else catches up.
Related Read: Digital Lending Maturity Across Southeast Asia: A Market-by-Market Analysis
FinnOne Neo® 9.0 is built for that kind of shift, configurable enough to absorb new regulatory requirements without a re-platforming exercise, open enough to integrate with the fintech and payment ecosystems already in place market by market, and modular enough that institutions can adopt what they need, Islamic finance workflows, region-based repossession rules, bureau integrations, without carrying the weight of what they don’t.
Vietnam is our largest market in Southeast Asia, FinnOne Neo® 9.0 is that same commitment extended across the region, to Vietnam, the Philippines, Sri Lanka, Indonesia, Malaysia, and the institutions in each that are trying to turn AI from a talking point into something that actually shows up on their books, on a platform agile enough to keep up with wherever those markets go next.
The pressure on Southeast Asia’s lenders isn’t easing up, customer expectations, regulatory demands, and competition are all climbing at once. The institutions that get ahead of that now, with platforms built to handle it, are the ones that will still be setting the pace a few years from now.
Ready to see what FinnOne Neo® 9.0 can do for your institution? Explore what’s new, download the brochure, or book a demo.