FinnOne Neo®

 Lending

 Transaction Banking
 Financial Inclusion
 Technology



A business can be profitable on paper and still find itself short of cash.
It happens more often than one might expect – A large customer delays payment, a supplier changes its payment schedule, or an unexpected currency movement increases the cost of an overseas transaction yet none of these events necessarily changes the company’s financial performance immediately, yet each can affect how much cash is available to meet its obligations.
For treasury teams, the challenge is keeping track of these movements across the organisation – Bank balances, receivables, payment schedules and business forecasts rarely sit in one place, as stated bringing them together often involves spreadsheets, reports from different departments and a fair amount of manual reconciliation.
The difficulty becomes more apparent when something changes.
A payment that was expected on Monday may not arrive until Thursday, a subsidiary that appeared to have sufficient funds may suddenly need additional liquidity Meanwhile, another entity within the same organisation could be holding cash that might help address the shortfall. By the time these developments make their way into a consolidated report, treasury may already be working with an outdated picture.
This is one of the limitations of conventional cash flow forecasting, it has largely been built around estimating future balances at specific intervals. What it has not always been equipped to do is keep pace with the financial decisions and unexpected developments that influence those balances.
The EY India Corporate Treasury Survey 2025 highlights the extent of this challenge. More than 70% of treasury teams in India continue to depend on spreadsheets, while cash forecasting has emerged as one of the leading use cases for AI adoption. The survey, which gathered inputs from 85 treasury leaders, points towards a growing demand for better-connected financial information and more predictive capabilities.
The interest in AI is understandable – Treasury teams are dealing with increasingly complex financial environments, and manual processes make it difficult to respond at the speed businesses now expect.
AI-powered cash flow forecasting offers a way to approach this differently. Instead of relying solely on payment schedules and periodic updates, organisations can use historical transactions, current cash positions and changing business conditions to build a more informed picture of what lies ahead.
However, improving forecast accuracy is only one part of the opportunity. The larger question is what happens after a potential surplus or shortfall is identified. Can the system help treasury understand its options? Can it recommend an appropriate response? And, where the organisation permits it, can it carry out routine actions without waiting for manual intervention?
These questions are taking cash forecasting into a much broader conversation about autonomous treasury.
The Information Behind a Reliable Cash Forecast
Ask a treasury professional what goes into preparing a cash forecast, and the answer is unlikely to be a single report or system.
The information is spread across the organisation. Bank statements provide one part of the picture, while accounts receivable, accounts payable, procurement, payroll and business planning systems provide the rest.
A typical cash forecast may depend on:
- Current bank balances and transaction records.
- Outstanding customer invoices and expected collections.
- Supplier obligations and scheduled payments.
- Accounts receivable and accounts payable.
- Payroll, tax and debt repayment commitments.
- Sales projections and procurement requirements.
- Historical customer and supplier payment patterns.
- Interest rates, foreign exchange movements and other market indicators.
The challenge is that these sources do not necessarily speak the same language. Information may arrive at different times, reporting formats may vary between entities, and some transactions may not be reflected until they have been manually reconciled.
Treasury teams end up spending valuable time establishing whether the information is complete before they can use it to make decisions.
AI introduces another way of working with these inputs.
Take customer collections, for instance. An invoice may have a payment term of 30 days, but that does not necessarily mean the money will arrive on the thirtieth day. A customer may have a history of paying late, or its recent payment behaviour may suggest that an expected receipt could be delayed.
A forecasting model that considers these patterns has more information to work with than one relying exclusively on contractual due dates.
Improving the accuracy of cash inflow projections also depends on effective receivables management, where timely collection tracking, automated reconciliation and visibility into outstanding payments can help treasury teams make better-informed decisions.
The same applies to supplier payments. Historical transaction data can reveal recurring payment patterns, seasonal requirements and changes in spending behaviour that might otherwise be overlooked.
As new transactions are recorded, machine learning models can reassess their estimates. If a customer payment is delayed or a payment instruction changes, the forecast can reflect the new information rather than waiting for the next reporting cycle.
This does not make the underlying data any less important. A model working with incomplete or inaccurate records can produce misleading results, regardless of how sophisticated it is. Data quality and validation remain essential.
What changes is the amount of information treasury can consider and how quickly that information can be put to use.
Three Forecasting Horizons, Three Different Business Needs
Cash requirements change depending on how far ahead an organisation is looking.
A treasury team managing today’s payment obligations needs a very different level of detail from a CFO assessing funding requirements for the next financial year. Treating both decisions through a single forecasting approach can leave important gaps.
In practice, treasury forecasting needs to work across three-time horizons.
Near-term Forecasting: Intraday to Seven Days
At the operational level, the priority is knowing whether cash will be available when payments fall due.
This forecast relies on current bank balances, transaction feeds, payment queues, confirmed receipts and immediate financial obligations.
A treasurer might need to establish whether a particular account has enough funds for the day’s payments, whether another entity is approaching its minimum cash threshold or whether an expected customer receipt has failed to arrive.
These are immediate questions, and delays in answering them can have operational consequences.
AI can help by identifying unusual movements and highlighting transactions that could affect the projected cash position. If a significant receipt is delayed, for example, the system can flag the change and show which upcoming obligations may be affected.
There is also a practical difference in the reliability of information across forecasting periods. Near-term projections generally benefit from more current and confirmed transaction data. They are not immune to errors or unexpected events, but they usually involve fewer assumptions than forecasts extending several months into the future.
Medium-term Forecasting: Two to Thirteen Weeks
The focus changes when treasury looks several weeks ahead.
At this stage, the concern is less about completing today’s payment cycle and more about understanding how working capital requirements might develop.
Customer collections, supplier payment schedules, sales activity and seasonal business patterns all become important inputs.
A business may appear comfortable from a liquidity perspective today, but its position could look quite different in six weeks if several large customer payments are delayed or supplier obligations increase.
Treasury needs to identify these possibilities early enough to consider its options.
Some of the questions that matter at this stage include:
- When might the organisation need additional short-term funding?
- Is the current cash surplus likely to remain available?
- Could borrowing be reduced over the coming weeks?
- Are particular customer collections becoming less predictable?
- Is there flexibility in the timing of planned payments or investments?
AI can help assess historical transaction behaviour alongside updated business inputs to identify emerging patterns.
For example, if collections from a particular customer segment regularly slow down during a certain period, the forecast can account for that behaviour rather than assuming that every invoice will be settled on its contractual due date.
Medium-term forecasting is also where scenario analysis becomes useful. Treasury can compare different collection assumptions, spending patterns and funding requirements to understand how each might affect liquidity.
Long-term Forecasting: Three to Twelve Months and Beyond
Looking further ahead, the conversation moves towards financial planning.
The CFO and treasurer need to understand whether the organisation will have sufficient liquidity to support its business plans, meet debt obligations and fund planned investments.
Budgets, capital expenditure, debt maturities, interest-rate assumptions and foreign exchange exposure become central to the exercise.
An exact cash balance several months from now is difficult to establish with certainty. The business may grow faster than expected, operating costs may change or market conditions may shift.
The more useful question is what different financial scenarios could mean for the organisation.
For instance, what happens to liquidity if revenue falls below budget? Could higher interest rates increase borrowing costs? Would a change in currency values affect the cost of international obligations?
AI-supported scenario modelling can help evaluate these possibilities and show how different assumptions influence future liquidity.
For finance leaders, this creates a stronger basis for decisions around borrowing, capital allocation and financial resilience.
Understanding the Three Horizons
| Horizon | Primary Purpose | Key Information | Decisions Supported |
|---|---|---|---|
| Intraday to 7 days | – | Live balances, payment queues, confirmed receipts and obligations | Cash transfers, payment execution and immediate funding |
| 2-13 weeks | Working capital planning | Receivables, payables, payment behaviour and business activity | Short-term borrowing, investments and cash allocation |
| 3-12 months and beyond | Strategic financial planning | Budgets, capital expenditure, debt maturities and market scenarios | Funding strategy, capital allocation and financial resilience |
These periods should not be treated as separate forecasting exercises. What happens to cash today will influence the outlook for the next few weeks. Similarly, a change in business plans or market assumptions should eventually find its way into longer-term liquidity projections.
The value comes from keeping these views connected.
Why the Cash Position Alone Does Not Tell the Whole Story?
A consolidated cash balance can sometimes create a false sense of security.
Imagine a multinational organisation with several subsidiaries operating across different markets. Its treasury dashboard shows that the group has sufficient liquidity to meet its obligations for the coming week.
However, one subsidiary is expecting a sizeable customer receipt that has been delayed. Without that money, the entity could fall below its minimum cash requirement.
The group may have enough cash overall, but the funds are not necessarily available in the right place.
This is where the detail behind a forecast becomes important.
An AI-enabled system can help identify the delayed receipt, connect it to the affected account and show how the expected shortfall changes as new information becomes available.
It can also help treasury distinguish between a genuine liquidity concern and a temporary movement that does not require intervention.
Global liquidity management helps organisations gain visibility into cash positions across subsidiaries, banking relationships and currencies while identifying opportunities to optimise the use of available funds.
For this to work, a forecast needs to provide more than a projected number. Treasury should be able to understand:
- Where the cash is expected to be: A view of projected balances across bank accounts, currencies and business entities.
- What is influencing the position: The receipts, payments and business events responsible for changes in the forecast.
- How reliable the projection is: The assumptions behind the estimate, the quality of available information and the possible range of outcomes.
- What needs attention: Delayed transactions, unusual movements, missing information and accounts approaching minimum balance requirements.
- What has changed: An explanation of why the latest forecast differs from the previous one.
- What could be done next: Potential responses to an emerging liquidity surplus or shortfall.
The last point is particularly relevant. Treasury teams should not have to spend hours investigating every movement to establish whether it requires action. A system that can bring significant exceptions to their attention makes the forecasting process far more useful.
When Forecasting Starts Influencing Liquidity Decisions
There is a natural progression from knowing that a cash shortfall may occur to deciding how to deal with it.
Suppose an organisation’s forecast indicates that one of its accounts will have insufficient funds to meet upcoming obligations. The system could look at the wider liquidity position and assess the options available to treasury.
Perhaps another entity has surplus cash. Perhaps an approved credit facility is available. Alternatively, the organisation may have an investment that can be liquidated, depending on its terms and associated costs.
The decision is not simply about finding money to cover the gap. It involves comparing the financial and operational implications of each option.
For a projected shortage, possible responses include:
- Transferring available funds between authorised accounts or entities.
- Drawing on an approved credit facility.
- Liquidating an existing investment, where appropriate.
- Converting funds from another currency.
- Adjusting the timing of a non-critical payment, where commercially and contractually permissible.
A projected surplus presents a different set of choices. Treasury may consider investing the excess, reducing outstanding borrowing, funding another entity or retaining the funds to maintain an appropriate liquidity buffer.
An AI-enabled system can assess these alternatives against relevant treasury policies and present the options with the reasoning behind them.
Consider a business that is preparing to draw on a credit facility to cover an upcoming payment. A review of its wider cash position reveals that another subsidiary has surplus funds.
If the entities have an authorised arrangement that permits a transfer, moving the available cash could be more economical than taking on additional borrowing.
Such situations are also closely linked to the challenge of trapped cash, where funds exist within an organisation but cannot be accessed or deployed efficiently when needed.
This is the kind of decision where connected information makes a difference.
The treasurer still needs to assess whether the proposed action is permitted and appropriate. AI provides additional analysis and can help narrow down the options, but financial authority remains with the organisation.
Autonomous Treasury: How Much Should Technology Be Allowed to Do?
Autonomous treasury is often discussed as though the end goal is to remove human involvement from financial operations.
That is neither necessary nor particularly practical.
Treasury decisions involve money, regulatory obligations, internal policies and financial risk. Giving a system unrestricted authority over these activities would introduce a different set of problems.
A more realistic approach is to allow automation within clearly established boundaries.
Consider an organisation that operates a centralised cash management structure. At the end of the day, its treasury system identifies surplus funds in one account and a projected shortfall in another.
Both accounts are covered by an approved arrangement. The proposed transfer falls within the permitted transaction limit, and the required minimum balances will be maintained.
In complex banking environments, virtual account management can improve cash visibility across multiple accounts and banking relationships, helping treasury teams manage their liquidity more effectively.
In this situation, the organisation could authorise the system to execute the transfer automatically.
Now consider a decision involving substantial new borrowing or a significant foreign exchange transaction. The financial exposure is considerably different, and the organisation may require a senior treasurer or another authorised individual to approve it.
The distinction is not simply between automated and manual transactions. It is about deciding which activities can be trusted to operate within established controls.
That decision should account for:
- The value of the transaction and its potential financial impact.
- The reliability and freshness of the information supporting the decision.
- The authorised account and entity relationships.
- Legal and regulatory requirements.
- The organisation’s risk appetite.
- Existing approval and authorisation arrangements.
Under this model, AI can identify an opportunity, evaluate the available options and carry out routine activities where permission has already been granted.
People remain responsible for setting the rules, reviewing exceptions and taking ownership of material financial decisions.
The objective is to give treasury professionals more time for work that requires financial judgement, rather than having them spend a significant part of their day gathering information and evaluating routine transactions.
What Changes for the CFO and Treasurer?
As treasury systems become more predictive, the information available to finance leaders becomes more useful. However, the CFO and treasurer will not necessarily use that information in the same way.
For the CFO, the concern is the organisation’s financial position as a whole. The focus is on whether the business has sufficient liquidity to support its plans, how much funding it may require and what financial risks could affect future performance.
The information typically includes:
- Consolidated cash and available liquidity.
- Funding requirements and liquidity headroom.
- Forecast confidence and downside scenarios.
- Major financial and market exposures.
- Free cash flow and working capital.
- Implications for capital allocation and investment decisions.
The treasurer needs to work at a more operational level.
They need to know which accounts hold the available funds, which payments are approaching, where a shortfall could emerge and whether a transfer or funding action is required.
This involves a closer look at:
- Cash positions by bank account, entity and currency.
- Accounts approaching minimum balance thresholds.
- Forecast exceptions and the reasons behind them.
- Upcoming receipts, payments and funding requirements.
- Available liquidity options.
- Transactions awaiting approval.
- Data gaps and reconciliation issues.
A connected treasury platform can provide both views using the same underlying information.
The CFO can concentrate on financial resilience and capital allocation, while the treasurer manages liquidity positioning, operational requirements and execution.
Neither perspective works particularly well in isolation, strategic funding decisions depend on the quality of operational cash information, just as daily liquidity management needs to reflect the organisation’s broader financial plans.
Banks and the Importance of Treasury Connectivity
One aspect of cash flow forecasting that deserves particular attention is the role of banks.
An organisation’s financial information is distributed across its banking relationships. Current balances, transaction details, payment status and available credit are not necessarily accessible through a single banking channel.
For businesses operating across multiple markets, this becomes even more complicated. Different banks, account structures, currencies and payment arrangements all contribute to the organisation’s overall liquidity position.
Banks provide much of the infrastructure that makes treasury operations possible, including:
- Account balances and transaction information.
- Payment initiation and status updates.
- Cash pooling and sweeping arrangements.
- Deposits and short-term investment products.
- Credit facilities and borrowing services.
- Foreign exchange and other financial services.
The ability to bring this information together is central to effective treasury management.
APIs and host-to-host connections allow organisations to exchange information with banking partners and integrate it with their treasury systems. Structured financial messaging also helps make transaction information easier to interpret across different systems.
ISO 20022 is particularly relevant in this context because its richer, structured data supports more consistent communication of financial information.
For a multinational organisation, the treasury platform may need to connect with a global banking partner for centralised liquidity arrangements while maintaining relationships with regional banks for local payments, accounts and credit facilities.
The aim is to establish a consolidated view without losing the account-level detail required for day-to-day decisions.
There is little value in introducing sophisticated forecasting models if the information reaching them is incomplete or outdated. Banking connectivity and data consistency need to be addressed alongside the intelligence being built on top of them.
Responsible AI and the Need for Financial Control
The move towards more autonomous treasury also raises an important question: who is accountable when a system makes the wrong recommendation or executes an inappropriate transaction?
It is a question that cannot be left until after implementation.
AI models work with historical information, changing patterns and probability-based estimates. Their outputs can be useful, but they should not be treated as unquestionable financial instructions.
Organisations need to establish clear rules around what the system can access, what it can recommend and which actions it is authorised to execute.
A responsible approach should cover several areas.
- Data ownership and model performance: Someone must be accountable for the quality of the information entering the system, the way models are maintained and how their performance is assessed.
- Explainability: Treasury teams should be able to understand what influenced a forecast or recommendation. A proposed transaction should not appear without a clear explanation of its underlying rationale.
- Financial limits: Automated transactions must operate within approved thresholds. The level of authority should reflect the value and risk of the activity.
- Human approval: Material transactions, unusual exceptions and decisions involving significant financial exposure should remain subject to appropriate human oversight.
- Security and compliance: Existing fraud prevention, sanctions screening, regulatory requirements and access controls must remain effective.
- Audit trails: The organisation should be able to trace recommendations, approvals, modifications and executed transactions.
- Ongoing monitoring: Forecast accuracy, changes in model performance and unexpected outcomes need to be reviewed regularly.
- Exception management: Automated activity should be paused when information is incomplete, inconsistent or outside the limits established by the organisation.
These requirements bring treasury, technology, risk, compliance and audit teams into the same conversation.
The important consideration is not simply whether a model can decide that it is whether the organisation can understand that decision, establish that it was permitted and demonstrate who remains accountable for the outcome.
Making the Move Towards Autonomous Treasury
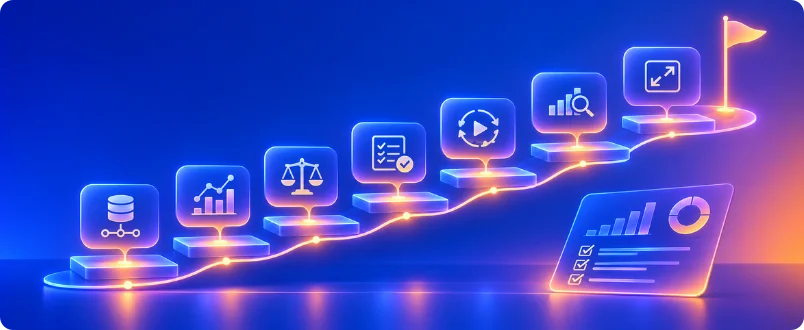
Organisations do not need to automate every treasury activity to benefit from AI.
In fact, starting with too many processes at once can make implementation more difficult, particularly when underlying data and banking connectivity still need attention.
A more sensible approach is to identify a specific problem and build from there.
- Find a problem worth solving: Start with an area where the existing process creates recurring difficulties. This could be inaccurate short-term forecasts, delayed visibility into customer collections or the time spent preparing liquidity reports.A clearly defined problem makes it easier to establish what the technology needs to achieve.
- Establish the data foundation: Identify the information required to address that problem. Bring together relevant bank, receivables, payables and business data, and assess whether it is accurate, consistent and available at the required frequency.
- Improve the quality of forecasting: Introduce AI capabilities to analyse transaction patterns, refresh projections and highlight the factors affecting the expected cash position. Treasury teams should be able to see not only the forecast but also the assumptions and exceptions behind it.
- Move towards decision support: Once the forecasts become more dependable, the system can begin comparing available liquidity options against established treasury policies. Record which recommendations are accepted, changed or rejected. This provides useful information about how well the system’s recommendations align with actual business decisions.
- Choose a controlled activity for automation: Identify a routine transaction that can be carried out within approved limits. A suitable starting point could involve an authorised internal cash transfer, subject to the organisation’s account arrangements and controls.
- Assess the business impact: Measure the results using indicators that matter to treasury. These could include forecast accuracy, idle cash, borrowing costs, time taken to make liquidity decisions, manual intervention and control exceptions.
- Expand when the business is ready: Additional activities, accounts and entities can be brought into the process once the organisation has established that the data, controls and business outcomes are dependable.
This approach avoids treating autonomy as an implementation milestone that needs to be reached as quickly as possible. It allows organisations to establish confidence in the technology while retaining control over their financial operations.
The Next Step in Treasury Transformation
For years, cash flow forecasting has been an exercise in bringing financial information together, estimating future balances and reporting the results to finance leaders.
That responsibility is not going away. What is changing is what organisations expect from the process.
A forecast that tells treasury how much cash may be available next week is useful. One that also identifies why the position could change, which account may face a shortfall and what options are available gives the organisation considerably more to work with.
AI is making this possible by connecting information across business functions, recognising patterns in financial transactions and helping treasury assess potential liquidity requirements earlier.
When these capabilities are supported by dependable banking connectivity, well-defined treasury policies and appropriate approval structures, the possibilities extend beyond forecasting. Routine liquidity decisions can increasingly be evaluated and, where permitted, executed with less manual intervention.
There will be differences in how far organisations can take this. Data maturity, regulatory requirements, existing banking infrastructure and internal risk appetite will all influence the pace of adoption.
Nor does every financial decision need to be automated.
The more meaningful shift is in how treasury uses the information available to it. Rather than spending most of its time establishing where cash stands, the function can devote greater attention to understanding what might change and how the organisation should respond.
The real measure of progress in cash flow forecasting will not be how quickly a system produces a number. It will be whether that information helps the business make a better financial decision, at the point when it matters.
Explore FinnAxia®, Nucleus Software’s transaction banking platform, to learn more about connected banking capabilities across payments, receivables and liquidity management.